

Binance’s perpetual tied to SOXL, a leveraged semiconductor ETF, recorded a 5.9% opening-to-low fall in the mark price used for margin risk during the 21:00–22:00 UTC hour on Saturday, Oct. 17. All 60 sampled minute-close gaps between that mark and its reference index stayed below 3%.
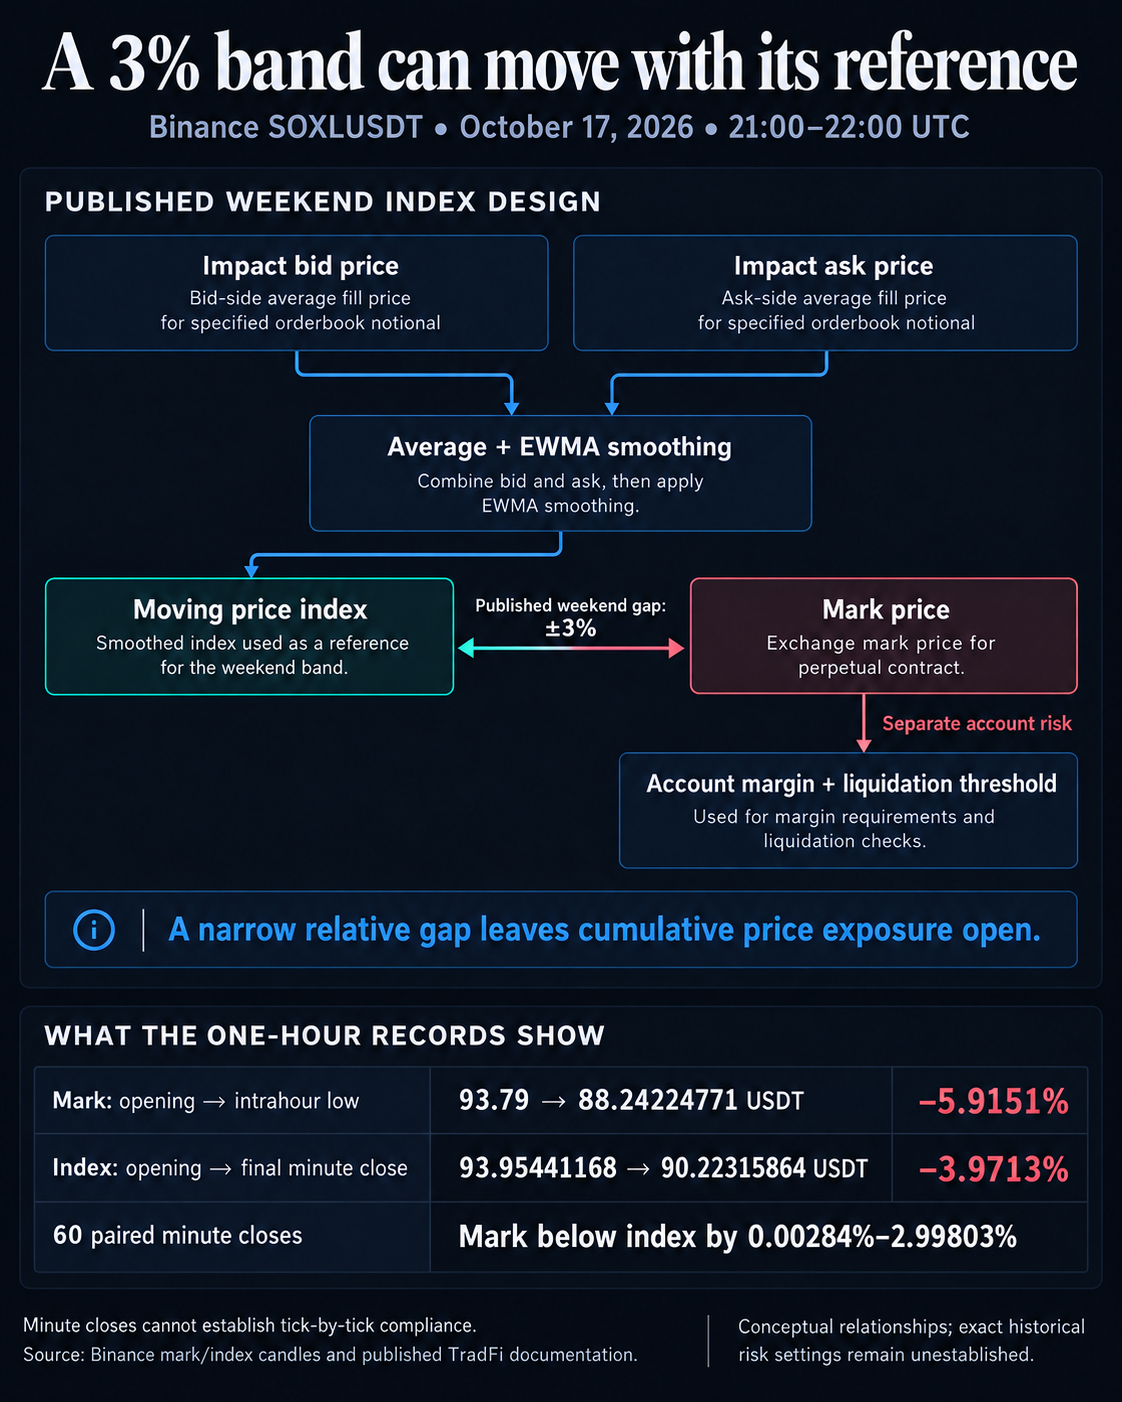
The two observations measure different risks. Binance’s published weekend band constrains the mark’s distance from the index at a particular moment. The index can move away from the trader’s entry price, leaving cumulative price exposure open. In the sampled hour, the index itself fell almost 4%.
For a leveraged trader, that distinction leaves room for losses and liquidation despite a narrow mark/index gap. A reference-price safeguard and the amount of collateral keeping a position open answer different questions.
Binance’s one-minute mark-price records show SOXLUSDT opening at 93.79 USDT at 21:00 UTC. The mark reached an intrahour low of 88.24 USDT within the 21:41 minute, a 5.9151% opening-to-low decline. It finished the final minute at 90 USDT, down 4% from the opening.
The corresponding index records show the reference moving from 93.95 USDT at the opening to 90.22 USDT at the final minute close, a 3.9% decline.
These are prices for a perpetual contract quoted and settled in Tether’s USDT, a stablecoin designed to track the dollar. The records describe Binance’s derivative rather than Saturday trades in SOXL shares on NYSE Arca.
| Series | 21:00 UTC opening | Final minute close | Opening-to-close change |
|---|---|---|---|
| SOXLUSDT mark | 93.79 USDT | 90 USDT | −4.0409% |
| SOXLUSDT index | 93.95441168 USDT | 90.22315864 USDT | −3.9713% |
Matching each mark candle with the index candle for the same minute gives 60 closing observations. At every one, the mark was below the index. The discounts ranged from about 0.00284% to 2.9%, all below the stated 3% weekend limit.
The low is an intraminute observation; the gap comparison uses matched minute closes. The sample covers one hour and cannot establish tick-by-tick compliance.
The reference can move with the market
Binance’s detailed TradFi FAQ, displaying a Sept. 23 update, describes a ±3% weekend and holiday mark/index constraint for equity-based perpetuals. It also reserves the right to adjust deviation constraints during extreme market conditions.
The index is the crucial part. Procedures 67 and 68.5 of Binance’s currently published Clearing Procedures describe an orderbook-derived reference during underlying-market weekends and other closures. It takes the average of impact bid and impact ask prices and smooths it with an exponentially weighted moving average.
That smoothing moderates how inputs feed into a reference while allowing the reference to move. If orderbook-derived inputs move lower, a smoothed index can move lower too, taking the level around which the mark is constrained with it.
The two percentage calculations therefore have different denominators. A mark/index gap compares two prices at the same time. A trader’s price return compares a later mark with an earlier price. A small gap between the current mark and index can coexist with a large move from an earlier entry price.
The distinction becomes visible when equity perpetuals continue trading while their underlying shares do not. The weekend index described in the procedures is derived from the orderbook rather than a newly traded NYSE Arca share price. Its level can therefore change during the closure.
Binance’s simpler learn-page summary still describes a fixed index outside underlying trading hours. That description differs from the detailed FAQ, which dates the replacement of fixed mode for equity perpetuals during maintenance, holidays and weekends to May 16, 2026, at 00:00 UTC. The documented change predates this October episode.
The SOXL specifications place rules, specifications and notices ahead of general guidance in their stated hierarchy. The dated FAQ and current orderbook procedure describe a moving reference, in contrast with the simpler summary’s fixed anchor.
Public descriptions also differ on the off-hours mark formula. Procedure 51 describes nonregular-session smoothing, while the detailed FAQ makes the mark formula conditional on the index mode. The exact historical rulebook revision, smoothing parameters and margin settings for this hour remain unestablished.
A price band is separate from the liquidation threshold
There are four prices or thresholds to keep apart: the last execution price, the reference index, the mark used for margin risk and the liquidation price calculated for a position.
The SOXL contract specifications, published May 15, identify the underlying asset as the price of one Direxion Daily Semiconductor Bull 3X ETF share on NYSE Arca. Holding the perpetual gives derivative exposure rather than ownership of that share.
Those specifications tie liquidation to the mark reaching the account’s applicable liquidation threshold. The calculation depends on the margin arrangement, including cross or isolated margin, rather than simply a 3% distance from the index.
The clearing procedures separately describe initial margin, maintenance margin and leverage tiers, and allow margin requirements to change, including for existing positions.
SOXL adds another distinct layer of leverage. Direxion targets 300% of the NYSE Semiconductor Index’s daily performance for SOXL and the inverse 300% for SOXS, before fees and expenses. Their daily objectives leave longer-period cumulative returns dependent on the return path.
That daily-reset behavior is separate from the leverage selected for an exchange perpetual.
MarginPad’s Oct. 17 UTC recap lists $11.3 million in SOXL liquidated positions across 1,043 events in its full-day, cross-exchange feed. The figure measures liquidated position value rather than investor cash losses.
A moving index lets both prices fall together. The 3% band limits their separation, while margin determines whether a leveraged position survives.
Credit: Source link